This year’s five rate rises have added the price of a top of the range LandCruiser to the average mortgage
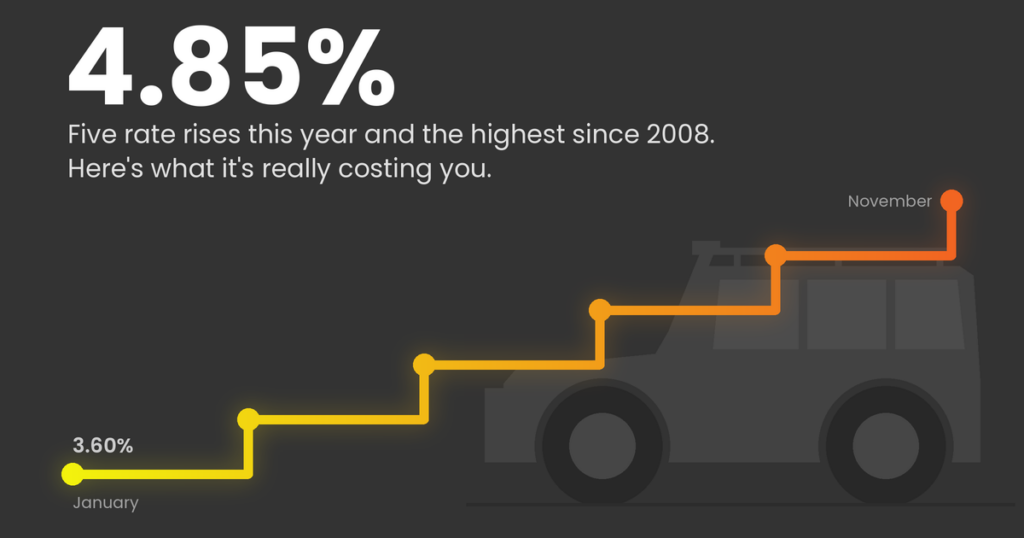
If you opened your banking app this afternoon and felt your stomach drop, I completely understand, because the Reserve Bank has just lifted the cash rate to 4.85%, which is the fifth rise this year and the highest it’s been since 2008.
I speak with people about their loans every day, and lately so many of those conversations start with some version of “I’m doing everything right, so why does it feel like I’m going backwards?” You’re paying more at the checkout, more at the bowser and now more on the mortgage as well, and if that’s where you’re at right now, I want you to know that none of this is your fault.
I can’t change what the RBA decided today, but what I can do is explain what it actually means for you in plain English, show you the real numbers and tell you exactly what I’d do if I was in your shoes.
What it’s costing you
About $175,000 is what this year’s five rises add to the average $731,000 mortgage over the rest of a 25 year loan if rates stay where they are, which is enough to buy an elite LandCruiser.

Worse, it’s coming out of the same budget that already has to cover groceries, fuel, power and everything else that’s gone up this year.
| Loan balance | Extra per month from today’s rise | Extra per month since January | Extra per year since January |
|---|---|---|---|
| $300,000 | $47 | $230 | $2,764 |
| $400,000 | $63 | $307 | $3,686 |
| $500,000 | $78 | $384 | $4,607 |
| $600,000 | $94 | $461 | $5,529 |
| $800,000 | $126 | $614 | $7,372 |
| $1,000,000 | $157 | $768 | $9,215 |
Work out your own number
How Australia compares
Central banks right around the world have been fighting the same inflation this year, but as you can see below, none of the G7 economies have leaned on their borrowers anywhere near as hard as ours has, with Australia now sitting on the highest rate of the lot after more rises than any of them.
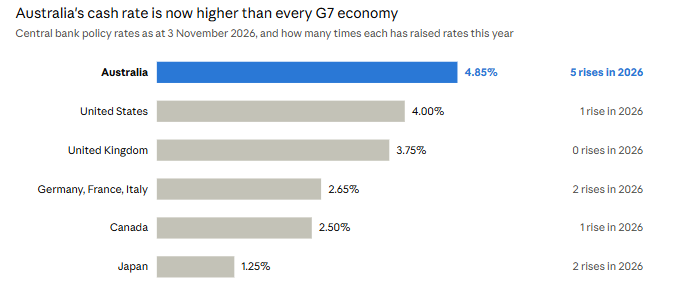
Policy rates as published on 3 November 2026. The US figure is the top of the Federal Reserve's 3.75% to 4.00% target range, and Germany, France and Italy all share the European Central Bank's main refinancing rate.
What it means for your car, boat or caravan loan
The good news: most car, boat and caravan loans are fixed for the whole term, so today's rise shouldn't change the repayments on the one you already have.
Here's some genuinely good news, because most car, boat and caravan loans in Australia are fixed for the whole term, which means if you already have one, today's rise shouldn't change your repayment at all (it's still worth checking your contract to be sure).
Where you will feel it is when you take out a new loan, because as lenders' own funding costs go up so do the rates they offer, so whether you need a reliable car to get to work, a ute for the business or you've been planning that caravan trip for years, the rate you lock in now matters a lot more than it did back in January.
Seriously, get pre-approved before you buy anything
Get pre-approved first. Most car loans are fixed for the whole term, so once you know your rate you know exactly what your repayment will be for the life of the loan, and you can work out what you can comfortably afford before you ever set foot in a dealership.
If there's one thing I'd ask you to take away from this whole article, it's to get pre-approved before you start shopping, and I honestly can't say it strongly enough.
Because most car, boat and caravan loans are fixed for the whole term, your repayment on day one is the same as your repayment on the very last day, so when rates are moving around as much as they are right now, a pre-approval is the clearest way to see exactly what you'll be paying each week and work out what you can genuinely afford alongside your mortgage, your bills and everything else that's gone up this year.
It also puts you in a much stronger position when you're actually buying, because you walk in knowing your limit, you're not being pushed into dealer finance on the spot, and you can put your energy into negotiating the price of the car instead of worrying about the loan.
With us, a pre-approval is one application that we compare across our panel of 40+ lenders, it won't leave a trail of enquiries on your credit file from lender after lender, and it shows you exactly where you stand before you commit to anything.
Get pre-approved for your car loan
What I'd do in your shoes
You can't control the cash rate, but you can control your next move, and a few small moves made now can add up to a lot over the next year.
- Find your real number. Check whether each of your loans is fixed or variable and what your new repayment is going to be, because not knowing is often more stressful than the number itself.
- Ask your lender for a better rate. Canstar estimates that borrowers who haven't renegotiated in five years could be paying around 7.34%, and a phone call costs you nothing, especially when lenders will often sharpen their rate for customers who simply ask.
- Look at the whole budget rather than one bill. Put your mortgage, car loan, credit cards and subscriptions all in one place, because it's much easier to find some room when you can see where everything is going.
- If you're struggling, speak up early. Lenders are required to consider hardship requests and it's far easier to sort something out before you miss a payment, so there's absolutely no shame in asking, and the National Debt Helpline on 1800 007 007 offers free and confidential help as well.
- If you're buying soon, get pre-approved first. Most car loans are fixed for the whole term (though we'll teach you some tricks that we apply to get you the best possible option), so a pre-approval tells you exactly what your repayment will be and what you can comfortably afford, and you're not making a finance decision on the spot at the dealership. Honestly, if you only do one thing on this list, make it this one.
- If you already have a car loan at a high rate, check whether refinancing makes sense. It's worth a look, as long as you factor in any fees or early exit costs before you make the switch.
Why comparing lenders matters more now
With one application we compare your options across 40+ lenders, and you deal with the same team here in Perth the whole way through.
That's exactly why I do this job, because with one application we compare your options across our full panel of 40+ lenders, you deal with one team here in Perth instead of a call centre, and we do all the legwork while protecting your credit score by not firing off applications to lender after lender.
I won't promise you a particular rate because honestly nobody can, I will promise to look properly and tell you straight what's actually available to you.
You don't have to work this out alone
This is a tough stretch for a lot of people and it's completely okay to feel worn down by it, so if you're buying a car, boat or caravan, or you'd just like someone to check whether your current loan still stacks up, I'd genuinely love to help.
Give us a call on 1300 212 200 (8:30am to 5:30pm Monday to Friday, 9am to 12pm Saturday) or get pre-approved online, and you'll speak to us, not robots and not people offshore.
This article is general information only and doesn't take into account your objectives, financial situation or needs. Figures are estimates and examples only, not a quote or an offer of credit. Lending criteria, fees and charges apply. Loans Unlimited, Australian Credit Licence 506875.